
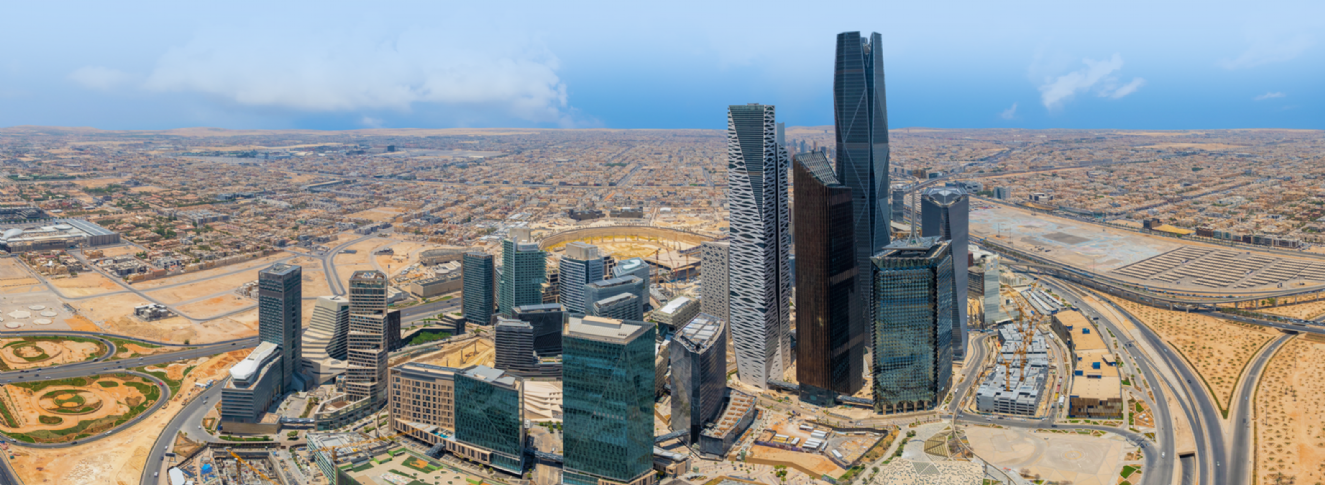
Riyadh's office market continued its transition towards greater stability during Q3 2026, with prime office occupancy remaining exceptionally high at 98% and rental growth beginning to moderate. Average asking rents remained broadly stable across the city's key office districts, reflecting a more measured leasing environment as occupiers increasingly prioritised flexibility, quality and long-term value. Despite a cautious approach to new leasing commitments, demand for high-quality Grade A office space remained supported by continued corporate investment and international business activity.
Occupier preferences continued to evolve during the quarter, with businesses favouring short-term lease renewals, immediately available office space and flexible workspace solutions. Zone A maintained the highest average asking rents at SAR 2,860 per sq m per annum, despite a marginal quarterly decline of 0.7%, while Zones B and C remained stable. Zone D recorded the strongest annual rental growth at 9.8%. Meanwhile, continued international corporate commitments, alongside improving business confidence and non-oil sector activity, highlighted Riyadh's ongoing appeal as a regional business hub.
Looking ahead, more than 2.5 million sq m of new Grade A office space is expected to enter the market by 2030, gradually easing supply constraints and providing occupiers with greater choice. As new developments are delivered, rental growth is expected to remain broadly stable, with increased flexibility in leasing terms and incentives supporting market activity. The continued expansion of flexible workspace offerings and a growing emphasis on quality and operational efficiency are expected to shape Riyadh's next phase of office market development.
For detailed insights into Riyadh's office market, read the full Q3 2026 report.